Concentration, Not Diversification What the 2026 startup reports really say
The 2026 startup reports are usually read as proof that the map is being redrawn. Read carefully, they say something closer to the opposite. In 2025 capital recovered, but only at the top of the stack, and the fastest-growing ecosystems are growing from small bases while the gap to the leader widens. Every figure here was checked against the source report before it was drawn.
- Late-stage funding
- +17%
- to ~US$210B in 2025
- Series A funding
- +2%
- to US$46.5B in 2025, near flat
- of late-stage AI-native funding
- 86%
- went to North America
- US score vs the UK
- 3.9×
- the #1 and #2 countries
Earn a fact-checker's badge in each interactive section. There are six.
Before anything else
Can you spot the wrong numbers?
Before writing this report I checked a summary post of both reports, line by line, and then checked my own check against the source text. Eight of its claims are below. Call each one: true, false or half-true. Then see what the reports actually say.
- 1 · The post saidGSER 2026
"Late-stage funding grew roughly 17% to US$210B."
- 2 · The post saidGSER 2026
"Q1 2026 Series A rounds surged 28%."
- 3 · The post saidGSER 2026
"North America captured 86% of late-stage global AI funding."
- 4 · The post saidStartupBlink 2026
"The Index benchmarks 1,500+ cities across 120 countries."
- 5 · The post saidStartupBlink 2026
"Singapore ranks 4th globally per capita."
- 6 · The post saidStartupBlink 2026
"StartupBlink tracks 1,213 unicorns."
- 7 · The post saidStartupBlink 2026
"United States: 633 unicorns (52%)."
- 8 · The post saidStartupBlink 2026
"Riyadh is now the Gulf's top-ranked hub, backed by Saudi Arabia's 97% growth."
1 · The recovery
The recovery is real, and it is top-heavy
"Funding has recovered" is true. What gets dropped is where it recovered. Switch between the averaged headline and the split by stage.
Dashed outline: the 2024 level, back-calculated from the growth rate.
The first signal from 2026
GSER adds that Q1 2026 Series A was up 28% over the 2025 quarterly average. One quarter against an average is not a trend, but it is the first sign that the bottom of the stack may be catching up. It is the number to watch.
What this meant for anyone raising in 2025
A company already at scale is raising into a market with 17% more capital than last year. A company raising its first institutional round is raising into a market that barely moved. The recovery narrative is most useful to the companies that needed it least.
2 · Follow the dollar
AI is not a sector in this data. It is most of the late stage.
Follow one late-stage dollar of 2025 down through the data. Each step is one click.
- All late-stage funding, 2025~US$210B · Startup Genome
- Into AI-native companiesUS$108B · about half of it
- Into North America86% of the AI-native money · about US$93B
- Left for every other regionabout US$15B of late-stage AI-native money
The compounding effect
These two facts multiply rather than sit side by side. If roughly half of late-stage capital goes to AI-native companies, and 86% of that flows to one region, then the largest pool of growth capital in the world is also the most geographically concentrated. Every ecosystem competing for late-stage AI rounds is competing for the 14% that is left.
3 · Fast growth, small base
Near-identical growth rates, very different absolute gains
Saudi Arabia grew 97%, Taiwan 41.1%, Singapore 24.4%. The United States grew 23.6%, the slowest of that group. But growth rates and absolute gains are different quantities, and here they point in opposite directions.
- United States314+23.6%
- United Kingdom80+13.2%
- Israel71+15.0%
- Singapore68+24.4%
- Canada50+9.0%
- Sweden41+15.5%
- Germany38+13.5%
- Switzerland36+13.7%
- Australia35+22.9%
- Netherlands35+11.8%
- United States+60.0
- Singapore+13.3
- United Kingdom+9.3
- Israel+9.3
- Australia+6.6
- Sweden+5.5
- Germany+4.5
- Switzerland+4.4
- Canada+4.1
- Netherlands+3.6
The US alone added about as many points as the next nine countries put together.
Catch-up calculator
How fast would Singapore have to grow, every year, to catch the United States? Move the sliders.
Catch-up in about 238 years, around 2264.
Illustrative arithmetic on index scores, not a forecast. Scores also move with methodology changes between editions.
The arithmetic that undercuts the "multipolar" reading
Singapore grew faster than the United States, 24.4% against 23.6%, and added about 13 points of score. The United States added about 60. On these numbers the gap between the leader and everyone else widened in 2026, even though the leader posted the lower growth rate. Reporting growth rates alone makes convergence look like it is happening when it is not.
4 · Unicorns
Unicorn concentration says the same thing
Each square is one unicorn, as printed on each country's page of the 2026 index. Switch between the ten countries side by side and the US against the next nine put together.
The United States has 620 unicorns; the next nine countries together have 411.
Treat every unicorn count as soft
The 2026 index lists unicorns country by country but publishes no global total, and the totals that circulate (1,113, 1,213) come from older or different snapshots. CB Insights, Hurun and Dealroom publish materially different totals for the same week. The concentration pattern holds across all of them. The specific integers do not.
5 · Where the map does move
Three shifts that are structural, not cyclical
Concentration is the dominant story, but not the only one. These three are worth tracking precisely because they do not reverse when interest rates move.
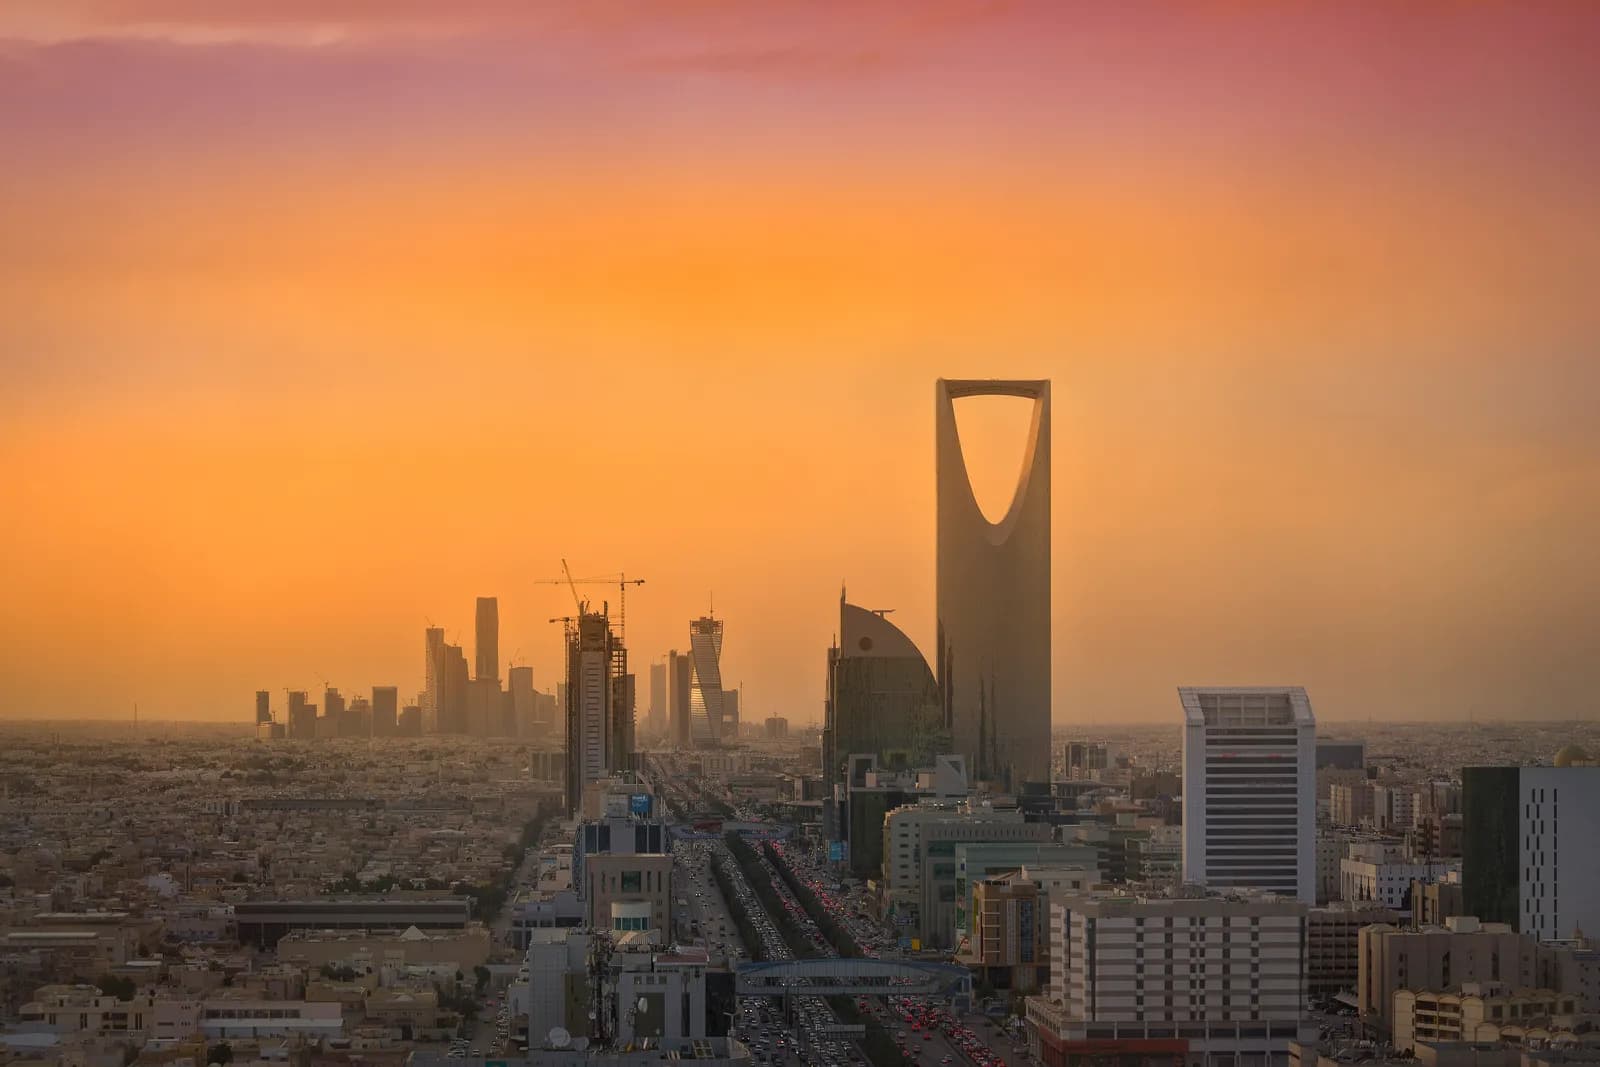
The Gulf's centre moved
Riyadh 42nd · Dubai 48th
Riyadh climbed 30 places, passed Dubai and was named StartupBlink's City of the Year. Saudi Arabia grew 97% and now leads the GCC.
State-directed capital allocation, not a funding cycle.
Taiwan entered the top 20
20th · +41.1%
Up 5 places, with the fastest growth in the top 20.
Hardware and semiconductor depth: the one asset base that cannot be copied quickly elsewhere.
DefenseTech broke out
Series A value +60%
Deal counts up about 15% over the past year.
Geopolitical procurement demand with long contract cycles: the least rate-sensitive category in the report.
6 · What follows
Five reads, and what would prove each one wrong
This section is interpretation, not a finding of either report. The figures above are theirs; the reading is mine. Take a side on each, then see what would falsify it.
The centre holds, the edges diversify
Early-stage is the real bottleneck
"AI company" stops being a category
Hardware's share should rise
State capital is now an ecosystem input
For founders
Where is your next round?
Pick your stage and your region. The answer is what this data says about the market you are walking into.
Flat Series A capital, outside the region that took 86% of late-stage AI money. Your local ecosystem's depth matters more than the global headline.
Data notes
Read these before quoting any number
- Two reports, two methodsStartupBlink ranks 1,556 cities and 100 countries on a composite score of startup quantity, quality and business environment. Startup Genome ranks about 40 ecosystems and focuses on funding and ecosystem value. Figures are labelled by source and are not interchangeable.
- Calculated figures are markedTwo numbers here are mine, not the reports': the AI-native share of late-stage funding (US$108B ÷ ~US$210B) and the absolute score gains (score ÷ (1 + growth), subtracted). Both are shown with their inputs.
- Score growth is not output growthStartupBlink's growth percentages measure change in a composite score, which also moves with methodology and coverage changes. They are not funding, revenue or company formation.
- Funding figures are 2025 full-yearGSER 2026 reports on 2025. Crunchbase put Q1 2026 global venture funding near US$300B, but that is a different source on a different basis and is not mixed in here.
- Checked twiceA second check against the source text changed three things: Series A +28% in Q1 2026 is in GSER after all; the 86% belongs to AI-native funding, while North America's share of all late-stage funding is 64%; and the unicorn counts here are the 2026 index's own, not the 2023 unicorn map.
Sources
- StartupBlink, Global Startup Ecosystem Index 2026 (PDF)
- Startup Genome, Global Startup Ecosystem Report 2026, Introduction
- Startup Genome, GSER 2026, Global Startup Ecosystem Ranking: Top 40
- StartupBlink, Top Unicorn Cities and Countries 2026
- Crunchbase News, Q1 2026 global venture funding (context only)